quantred 2.4.0__py3-none-any.whl
This diff represents the content of publicly available package versions that have been released to one of the supported registries. The information contained in this diff is provided for informational purposes only and reflects changes between package versions as they appear in their respective public registries.
- quantred/__init__.py +24 -0
- quantred/alphas/__init__.py +53 -0
- quantred/alphas/base.py +221 -0
- quantred/alphas/combine.py +260 -0
- quantred/alphas/horizon.py +153 -0
- quantred/alphas/refine.py +300 -0
- quantred/alphas/scorers.py +87 -0
- quantred/analytics/attribution.py +354 -0
- quantred/analytics/bootstrap.py +353 -0
- quantred/analytics/charts.py +393 -0
- quantred/analytics/excursion.py +185 -0
- quantred/analytics/execution_quality.py +180 -0
- quantred/analytics/exposure.py +167 -0
- quantred/analytics/htmlreport.py +1208 -0
- quantred/analytics/information.py +197 -0
- quantred/analytics/metrics.py +502 -0
- quantred/analytics/performance.py +639 -0
- quantred/analytics/reporting.py +1672 -0
- quantred/analytics/screening.py +190 -0
- quantred/analytics/series_comparison.py +303 -0
- quantred/analytics/trade_analytics.py +353 -0
- quantred/brokers/alpaca/broker.py +415 -0
- quantred/brokers/alpaca/factory.py +33 -0
- quantred/brokers/alpaca/market_data.py +166 -0
- quantred/brokers/base.py +220 -0
- quantred/brokers/dryrun.py +164 -0
- quantred/brokers/errors.py +70 -0
- quantred/cli.py +8619 -0
- quantred/costs/__init__.py +11 -0
- quantred/costs/base.py +126 -0
- quantred/costs/parametric.py +131 -0
- quantred/data/__init__.py +29 -0
- quantred/data/compute.py +332 -0
- quantred/data/edges.py +81 -0
- quantred/data/features.py +120 -0
- quantred/data/panel.py +61 -0
- quantred/data/scan.py +85 -0
- quantred/data/store.py +269 -0
- quantred/demo/__init__.py +22 -0
- quantred/demo/scanners.py +104 -0
- quantred/demo/strategies.py +125 -0
- quantred/engine/backtest.py +1206 -0
- quantred/engine/barcheck.py +228 -0
- quantred/engine/live.py +539 -0
- quantred/execution/decision.py +192 -0
- quantred/execution/flatten.py +302 -0
- quantred/execution/halt.py +165 -0
- quantred/execution/ledger.py +758 -0
- quantred/execution/live_trader.py +587 -0
- quantred/execution/order_id.py +83 -0
- quantred/execution/sizing.py +114 -0
- quantred/indicators/indicators.py +158 -0
- quantred/marketdata/base.py +62 -0
- quantred/marketdata/client.py +59 -0
- quantred/marketdata/session.py +112 -0
- quantred/marketdata/synthetic.py +74 -0
- quantred/marketdata/timeframe.py +125 -0
- quantred/mcp/__init__.py +6 -0
- quantred/mcp/selftest.py +139 -0
- quantred/mcp/server.py +2419 -0
- quantred/optimization/causality.py +607 -0
- quantred/optimization/config_store.py +300 -0
- quantred/optimization/optimizer.py +431 -0
- quantred/optimization/parallel.py +345 -0
- quantred/optimization/param_space.py +309 -0
- quantred/optimization/walk_forward.py +1254 -0
- quantred/portfolio/allocator.py +135 -0
- quantred/portfolio/benchmark.py +109 -0
- quantred/portfolio/optimizer.py +786 -0
- quantred/portfolio/policy.py +335 -0
- quantred/portfolio/posterior.py +208 -0
- quantred/research/__init__.py +30 -0
- quantred/research/agent.py +868 -0
- quantred/research/demo_proposals.py +222 -0
- quantred/research/llm.py +311 -0
- quantred/research/proposer.py +234 -0
- quantred/research/provider_errors.py +242 -0
- quantred/research/sandbox.py +340 -0
- quantred/risk/__init__.py +60 -0
- quantred/risk/base.py +218 -0
- quantred/risk/conditional.py +474 -0
- quantred/risk/exposures.py +88 -0
- quantred/risk/factor.py +119 -0
- quantred/risk/sample.py +89 -0
- quantred/risk/streaming.py +214 -0
- quantred/scanners/base.py +141 -0
- quantred/scanners/symbol_scanner.py +148 -0
- quantred/services/__init__.py +51 -0
- quantred/services/analysis.py +6082 -0
- quantred/services/audit.py +574 -0
- quantred/services/campaign.py +381 -0
- quantred/services/configs.py +282 -0
- quantred/services/data.py +172 -0
- quantred/services/dryrun.py +206 -0
- quantred/services/glossary.py +130 -0
- quantred/services/maintenance.py +314 -0
- quantred/services/registry.py +351 -0
- quantred/services/setup.py +1023 -0
- quantred/services/sizing.py +150 -0
- quantred/services/smallreal.py +450 -0
- quantred/settings.py +571 -0
- quantred/store/__init__.py +0 -0
- quantred/store/bars.py +660 -0
- quantred/store/trials.py +1804 -0
- quantred/strategies/base.py +643 -0
- quantred/strategies/signals.py +28 -0
- quantred/utils/errors.py +48 -0
- quantred/utils/extras.py +330 -0
- quantred/utils/logging_config.py +33 -0
- quantred/utils/numeric.py +46 -0
- quantred/utils/streaming.py +474 -0
- quantred/utils/timeutils.py +148 -0
- quantred-2.4.0.dist-info/METADATA +632 -0
- quantred-2.4.0.dist-info/RECORD +117 -0
- quantred-2.4.0.dist-info/WHEEL +4 -0
- quantred-2.4.0.dist-info/entry_points.txt +8 -0
- quantred-2.4.0.dist-info/licenses/LICENSE +21 -0
|
@@ -0,0 +1,632 @@
|
|
|
1
|
+
Metadata-Version: 2.5
|
|
2
|
+
Name: quantred
|
|
3
|
+
Version: 2.4.0
|
|
4
|
+
Summary: A layered, broker-agnostic algorithmic-trading research engine that is honest about how hard making money is.
|
|
5
|
+
Project-URL: Homepage, https://tradeflow.mk-dir.com/
|
|
6
|
+
Project-URL: Documentation, https://tradeflow.mk-dir.com/
|
|
7
|
+
Project-URL: Source, https://github.com/makedirectory/quantred
|
|
8
|
+
Project-URL: Issues, https://github.com/makedirectory/quantred/issues
|
|
9
|
+
Project-URL: Changelog, https://tradeflow.mk-dir.com/changelog
|
|
10
|
+
Author-email: Andrew Schwartz <andrew@mk-dir.com>
|
|
11
|
+
License-Expression: MIT
|
|
12
|
+
License-File: LICENSE
|
|
13
|
+
Keywords: alpaca,backtesting,mcp,quantitative-finance,trading,walk-forward
|
|
14
|
+
Classifier: Development Status :: 4 - Beta
|
|
15
|
+
Classifier: Intended Audience :: Financial and Insurance Industry
|
|
16
|
+
Classifier: Intended Audience :: Science/Research
|
|
17
|
+
Classifier: License :: OSI Approved :: MIT License
|
|
18
|
+
Classifier: Programming Language :: Python :: 3
|
|
19
|
+
Classifier: Programming Language :: Python :: 3.10
|
|
20
|
+
Classifier: Programming Language :: Python :: 3.11
|
|
21
|
+
Classifier: Programming Language :: Python :: 3.12
|
|
22
|
+
Classifier: Programming Language :: Python :: 3.13
|
|
23
|
+
Classifier: Programming Language :: Python :: 3.14
|
|
24
|
+
Classifier: Topic :: Office/Business :: Financial :: Investment
|
|
25
|
+
Classifier: Topic :: Scientific/Engineering :: Information Analysis
|
|
26
|
+
Requires-Python: >=3.10
|
|
27
|
+
Requires-Dist: alpaca-py>=0.35
|
|
28
|
+
Requires-Dist: numpy>=1.26
|
|
29
|
+
Requires-Dist: pandas>=2.0
|
|
30
|
+
Requires-Dist: pytz>=2024.1
|
|
31
|
+
Provides-Extra: ai
|
|
32
|
+
Requires-Dist: anthropic>=0.40; extra == 'ai'
|
|
33
|
+
Provides-Extra: dev
|
|
34
|
+
Requires-Dist: duckdb>=1.0; extra == 'dev'
|
|
35
|
+
Requires-Dist: hatchling>=1.21; extra == 'dev'
|
|
36
|
+
Requires-Dist: matplotlib>=3.8; extra == 'dev'
|
|
37
|
+
Requires-Dist: mcp<2,>=1.22; extra == 'dev'
|
|
38
|
+
Requires-Dist: ortools>=9.8; extra == 'dev'
|
|
39
|
+
Requires-Dist: polars>=1.25; extra == 'dev'
|
|
40
|
+
Requires-Dist: pyarrow>=14; extra == 'dev'
|
|
41
|
+
Requires-Dist: pytest>=8.0; extra == 'dev'
|
|
42
|
+
Requires-Dist: ruff>=0.6; extra == 'dev'
|
|
43
|
+
Requires-Dist: scikit-learn>=1.4; extra == 'dev'
|
|
44
|
+
Provides-Extra: mcp
|
|
45
|
+
Requires-Dist: mcp<2,>=1.22; extra == 'mcp'
|
|
46
|
+
Provides-Extra: openai
|
|
47
|
+
Requires-Dist: openai>=1.40; extra == 'openai'
|
|
48
|
+
Provides-Extra: optimize
|
|
49
|
+
Requires-Dist: scikit-learn>=1.4; extra == 'optimize'
|
|
50
|
+
Provides-Extra: portfolio
|
|
51
|
+
Requires-Dist: ortools>=9.8; extra == 'portfolio'
|
|
52
|
+
Provides-Extra: store
|
|
53
|
+
Requires-Dist: duckdb>=1.0; extra == 'store'
|
|
54
|
+
Requires-Dist: polars>=1.25; extra == 'store'
|
|
55
|
+
Requires-Dist: pyarrow>=14; extra == 'store'
|
|
56
|
+
Provides-Extra: viz
|
|
57
|
+
Requires-Dist: matplotlib>=3.8; extra == 'viz'
|
|
58
|
+
Description-Content-Type: text/markdown
|
|
59
|
+
|
|
60
|
+
# QuantRed
|
|
61
|
+
|
|
62
|
+
[](https://github.com/makedirectory/quantred/actions/workflows/ci.yml)
|
|
63
|
+
[](https://tradeflow.mk-dir.com/)
|
|
64
|
+
|
|
65
|
+
A small, **layered**, **broker-agnostic** algorithmic-trading **research
|
|
66
|
+
engine** — and an honest one, which mostly means it's very good at telling you
|
|
67
|
+
your brilliant strategy is actually noise. It scans markets, tests strategies,
|
|
68
|
+
validates them out-of-sample, allocates portfolios, and exposes the whole
|
|
69
|
+
research surface to AI agents **without ever handing them order-execution
|
|
70
|
+
authority**. It ships with an [Alpaca](https://alpaca.markets) adapter, but
|
|
71
|
+
everything above the broker layer is vendor-neutral.
|
|
72
|
+
It scans a universe of symbols, runs a strategy over them, and either **backtests**
|
|
73
|
+
on history or **trades live** (paper by default) — with optional **parameter
|
|
74
|
+
optimization**, **walk-forward validation**, and **constraint-solver portfolio
|
|
75
|
+
allocation**.
|
|
76
|
+
|
|
77
|
+
Full docs — usage guide, engineering wiki, and
|
|
78
|
+
[changelog](https://tradeflow.mk-dir.com/changelog) — live at
|
|
79
|
+
**[tradeflow.mk-dir.com](https://tradeflow.mk-dir.com/)**.
|
|
80
|
+
|
|
81
|
+
> Making money in markets is genuinely hard. This project won't change that — but
|
|
82
|
+
> it will at least stop you from fooling yourself quite so quickly, which is most
|
|
83
|
+
> of the battle.
|
|
84
|
+
|
|
85
|
+
Designed to be easy to try and easy to read:
|
|
86
|
+
|
|
87
|
+
- **No TA-Lib / no native build step** — indicators are pure pandas/numpy, so
|
|
88
|
+
`uv sync` is all you need and the Docker image carries no compiler toolchain.
|
|
89
|
+
- **Broker-agnostic** — everything is written against a `Broker` /
|
|
90
|
+
`MarketDataProvider` interface. Alpaca is the first implementation; dropping in
|
|
91
|
+
another venue means writing one adapter, nothing else.
|
|
92
|
+
- **Strict separation of concerns** — each layer does one job (see below).
|
|
93
|
+
|
|
94
|
+
> ⚠️ Educational software. Trading is risky; use paper trading. No warranty.
|
|
95
|
+
|
|
96
|
+
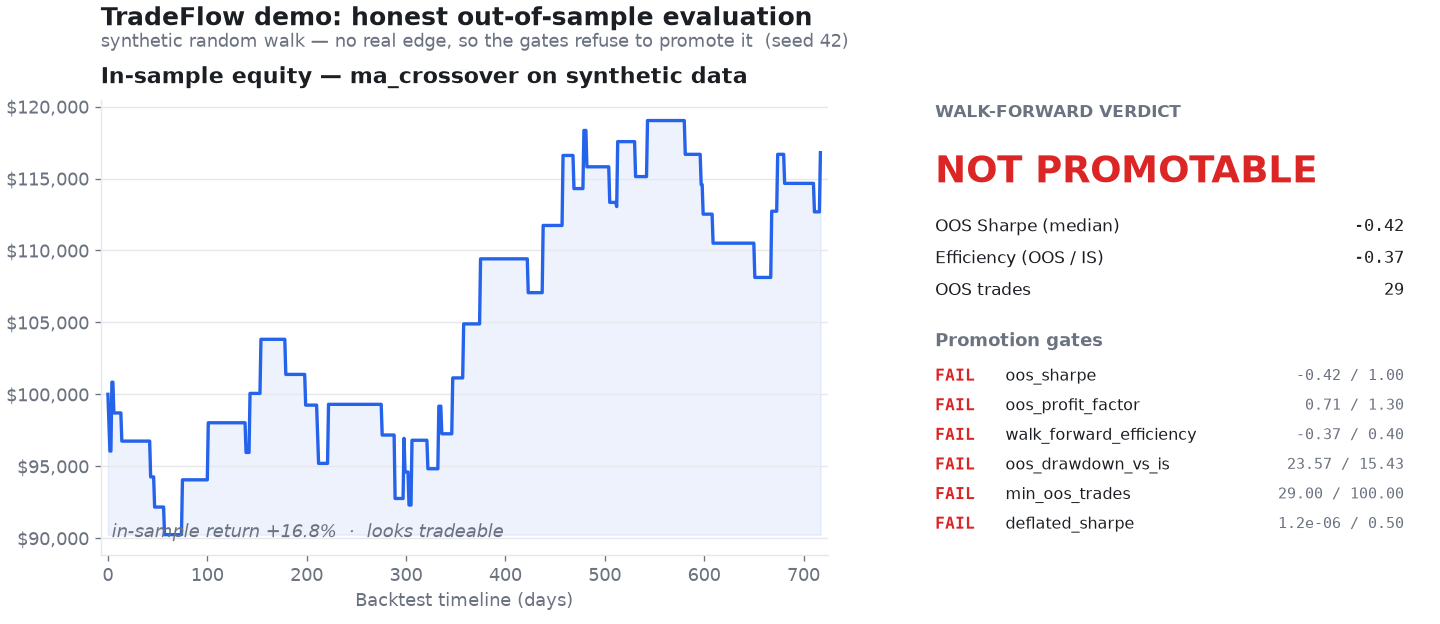
|
|
97
|
+
|
|
98
|
+
*`make demo` runs the whole pipeline on synthetic data (no keys, no network) and
|
|
99
|
+
renders this: a strategy that looks profitable in-sample, and the out-of-sample
|
|
100
|
+
verdict that calls it noise. The refusal is the product. The same panels render
|
|
101
|
+
for any run — pass `--chart PATH` to `backtest` or `walkforward`.*
|
|
102
|
+
|
|
103
|
+
## The mental model: two clocks
|
|
104
|
+
|
|
105
|
+
The one idea that explains everything else — QuantRed runs on **two clocks that
|
|
106
|
+
never touch**:
|
|
107
|
+
|
|
108
|
+
- **Research clock** (offline, slow, exploratory): backtest → optimize →
|
|
109
|
+
walk-forward, plus the optional AI agent. Non-determinism and LLMs are allowed
|
|
110
|
+
here. It only ever *proposes* — writing provenance-stamped configs to disk.
|
|
111
|
+
- **Trade clock** (live, deterministic, LLM-free): `live bar → signal → order`.
|
|
112
|
+
No model sits in the order path, so there's nothing to prompt-inject and nothing
|
|
113
|
+
non-deterministic to debug when real money is at stake.
|
|
114
|
+
|
|
115
|
+
**Promotion is a manual human step** — automation never flips `PAPER_TRADE` or
|
|
116
|
+
places an order. The [MCP server](#agent-integration-mcp) enforces this
|
|
117
|
+
*structurally*: it builds only a data client, so it physically cannot trade. See
|
|
118
|
+
the [architecture docs](https://tradeflow.mk-dir.com/engineering/architecture)
|
|
119
|
+
for the full picture.
|
|
120
|
+
|
|
121
|
+
## Requirements
|
|
122
|
+
|
|
123
|
+
You need **either** of these — not both:
|
|
124
|
+
|
|
125
|
+
- **[uv](https://docs.astral.sh/uv/getting-started/installation/)** — the Python
|
|
126
|
+
package manager used to run everything locally, **or**
|
|
127
|
+
- **[Docker](https://docs.docker.com/get-docker/)** — to build and run the app in
|
|
128
|
+
a container (no local Python or uv needed).
|
|
129
|
+
|
|
130
|
+
The `Makefile` targets run through **uv** (e.g. `make backtest` → `uv run …`), and
|
|
131
|
+
there are separate **Docker** targets (`make docker-build`, `make docker-run`).
|
|
132
|
+
Pick whichever you prefer.
|
|
133
|
+
|
|
134
|
+
Either way you'll need free Alpaca **paper-trading** API keys from the
|
|
135
|
+
[Alpaca dashboard](https://app.alpaca.markets/) → *Paper Account → API Keys*.
|
|
136
|
+
|
|
137
|
+
## Quickstart (install it)
|
|
138
|
+
|
|
139
|
+
No clone needed — install the command and run the offline demo:
|
|
140
|
+
|
|
141
|
+
```bash
|
|
142
|
+
uv tool install 'quantred[mcp,viz]' # or: python -m pip install 'quantred[mcp,viz]'
|
|
143
|
+
quantred demo # full pipeline on synthetic data, no keys
|
|
144
|
+
quantred init # your free Alpaca paper keys, and optionally a model
|
|
145
|
+
# provider for `research` (skipping it is fine)
|
|
146
|
+
quantred init --check # what is ready, for which task, and the next step
|
|
147
|
+
quantred init --probe-model --provider anthropic --for research # optional: one tiny billed request
|
|
148
|
+
quantred verdict --scanner none --symbols AAPL,MSFT,NVDA,AMZN,GOOGL,META,AVGO,JPM,XOM,UNH,COST,WMT \
|
|
149
|
+
--start 2024-01-01 --end 2024-12-31
|
|
150
|
+
claude mcp add quantred -- quantred mcp # connect an MCP client; it launches the server
|
|
151
|
+
quantred mcp --self-test # confirm discovery works without a chat client
|
|
152
|
+
```
|
|
153
|
+
|
|
154
|
+
Optional capabilities are extras (charts, the MCP server, the model SDKs). Adding one
|
|
155
|
+
later with `uv tool` replaces the environment, so list every extra you want — the
|
|
156
|
+
[extras guide](https://tradeflow.mk-dir.com/usage/extras) has the table and the exact
|
|
157
|
+
commands. `quantred init --check --for <task>` prints the one you need for that task, and a
|
|
158
|
+
command that needs a missing extra prints it with your current extras filled in.
|
|
159
|
+
|
|
160
|
+
**→ [Getting started](https://tradeflow.mk-dir.com/usage/getting-started)** walks the
|
|
161
|
+
whole path: install → keys → your first real result → Claude connected. Six steps,
|
|
162
|
+
the first two with no keys and no network.
|
|
163
|
+
|
|
164
|
+
The distribution and the command are both **`quantred`**; the importable package is
|
|
165
|
+
`quantred`; no `tradeflow` command is installed with it. If you installed the older
|
|
166
|
+
`tradeflow-engine`, its final release (2.3.1) is a transition package that depends on
|
|
167
|
+
`quantred`, so upgrading it moves you across without breaking old scripts, MCP configs or
|
|
168
|
+
packs importing `tradeflow` (the alias raises a `DeprecationWarning`, shown under `-W default` or in test runs). A private pack needs its imports
|
|
169
|
+
changed from `tradeflow` to `quantred` before you drop it. The steps are in
|
|
170
|
+
[migrating to QuantRed](https://tradeflow.mk-dir.com/usage/migrating-to-quantred).
|
|
171
|
+
|
|
172
|
+
State (the research journal, trial store, bar cache, promoted configs) lives in
|
|
173
|
+
`~/.tradeflow` — for an installed copy and for a checkout alike. `quantred --version`
|
|
174
|
+
prints which copy is running and where its state is; override with `TRADEFLOW_HOME`.
|
|
175
|
+
|
|
176
|
+
## Quickstart (from a checkout)
|
|
177
|
+
|
|
178
|
+
```bash
|
|
179
|
+
# 1. Install uv: https://docs.astral.sh/uv/
|
|
180
|
+
# 2. Install dependencies
|
|
181
|
+
make install # uv sync --inexact
|
|
182
|
+
|
|
183
|
+
# 3. See it work — no keys, no network
|
|
184
|
+
make demo # full pipeline on synthetic data + verdict
|
|
185
|
+
|
|
186
|
+
# 4. Point it at real data: guided setup for your free Alpaca paper keys
|
|
187
|
+
make init # writes .env, checks the keys, says what's next
|
|
188
|
+
# (make check re-runs the diagnostics any time)
|
|
189
|
+
|
|
190
|
+
# 5. Try it (preconfigured combos)
|
|
191
|
+
make scan # which symbols are flagged right now?
|
|
192
|
+
make backtest # scan -> demo strategy -> report
|
|
193
|
+
make live # paper-trade the scanned universe
|
|
194
|
+
```
|
|
195
|
+
|
|
196
|
+
## Docker (a local dev stack, not an easier install)
|
|
197
|
+
|
|
198
|
+
Docker is itself a prerequisite, so `uv tool install` above is the simpler way to
|
|
199
|
+
just try this. What compose adds is a long-running MCP server and docs site with
|
|
200
|
+
state on named volumes that survives container replacement:
|
|
201
|
+
|
|
202
|
+
```bash
|
|
203
|
+
make up # MCP + persistent state. Never starts trading.
|
|
204
|
+
make down # stop; your trial history survives
|
|
205
|
+
|
|
206
|
+
docker compose run --rm demo # offline, no keys
|
|
207
|
+
docker compose run --rm verdict --scanner none \
|
|
208
|
+
--symbols AAPL,MSFT,NVDA,AMZN,GOOGL,META,AVGO,JPM,XOM,UNH,COST,WMT \
|
|
209
|
+
--start 2024-01-02 --end 2024-12-31
|
|
210
|
+
```
|
|
211
|
+
|
|
212
|
+
`live` is profile-gated and is never started by `up` — turning the machine on must
|
|
213
|
+
not turn trading on. See [Running in Docker](https://tradeflow.mk-dir.com/usage/docker).
|
|
214
|
+
|
|
215
|
+
Run `make help` to see every target. Anything is overridable inline:
|
|
216
|
+
|
|
217
|
+
```bash
|
|
218
|
+
make backtest SYMBOLS=AAPL,MSFT,NVDA START=2024-06-01 END=2024-09-01 CAPITAL=50000
|
|
219
|
+
```
|
|
220
|
+
|
|
221
|
+
Or call the CLI directly:
|
|
222
|
+
|
|
223
|
+
```bash
|
|
224
|
+
uv run python main.py backtest --strategy demo_trend --scanner demo_volume \
|
|
225
|
+
--symbols NVDA,META,TSLA --start 2024-01-02 --end 2024-04-01
|
|
226
|
+
```
|
|
227
|
+
|
|
228
|
+
## See it run
|
|
229
|
+
|
|
230
|
+
`make demo` runs the entire pipeline on a seeded random walk — no keys, no
|
|
231
|
+
network — and ends in a promotion verdict. The point isn't a winning strategy;
|
|
232
|
+
it's that the **refusal to promote a noise strategy is the product**:
|
|
233
|
+
|
|
234
|
+
```text
|
|
235
|
+
$ make demo
|
|
236
|
+
|
|
237
|
+
======================================================================
|
|
238
|
+
QuantRed demo — synthetic data, no API keys, no network
|
|
239
|
+
(a seeded random walk: realistic-looking, no actual edge)
|
|
240
|
+
======================================================================
|
|
241
|
+
|
|
242
|
+
1) In-sample backtest of every registered strategy
|
|
243
|
+
In-sample, almost anything looks tradeable. That's the trap.
|
|
244
|
+
|
|
245
|
+
STRATEGY RETURN SHARPE TRADES
|
|
246
|
+
---------------------------------------
|
|
247
|
+
demo_trend 14.74% 0.48 45
|
|
248
|
+
|
|
249
|
+
2) Walk-forward validation of 'demo_trend' (the honest scorecard)
|
|
250
|
+
Optimize in-sample, score out-of-sample across folds, then gate it.
|
|
251
|
+
|
|
252
|
+
OOS Sharpe (median): -0.27 efficiency (OOS/IS): -0.19 OOS trades: 25
|
|
253
|
+
|
|
254
|
+
Promotion gates:
|
|
255
|
+
[FAIL] oos_sharpe: -0.27 (threshold 1.20)
|
|
256
|
+
[FAIL] oos_profit_factor: 0.74 (threshold 1.30)
|
|
257
|
+
[FAIL] walk_forward_efficiency: -0.19 (threshold 0.40)
|
|
258
|
+
[PASS] oos_drawdown_vs_is: 10.59% (threshold 15.41%)
|
|
259
|
+
[FAIL] min_oos_trades: 25 (threshold 100)
|
|
260
|
+
[FAIL] deflated_sharpe: <0.001 (threshold 0.500)
|
|
261
|
+
|
|
262
|
+
Verdict: NOT promotable
|
|
263
|
+
|
|
264
|
+
No edge in a random walk → the gates refuse to promote it. That refusal
|
|
265
|
+
is the product. Point QuantRed at real data:
|
|
266
|
+
quantred init add your free Alpaca paper keys
|
|
267
|
+
quantred verdict then run the whole pipeline on real market data
|
|
268
|
+
```
|
|
269
|
+
|
|
270
|
+
That is one strategy because a bare install ships one. Anything you install
|
|
271
|
+
alongside it appears in the same table, scored the same way.
|
|
272
|
+
|
|
273
|
+
Notice the arc: `demo_trend` looks tradeable in-sample (+14.7%, Sharpe 0.48), but
|
|
274
|
+
once it's optimized in-sample and scored **out-of-sample** the edge evaporates
|
|
275
|
+
(median OOS Sharpe −0.26) and all but one promotion gate fails. That's
|
|
276
|
+
[walk-forward validation](https://tradeflow.mk-dir.com/engineering/walk-forward)
|
|
277
|
+
doing its job.
|
|
278
|
+
|
|
279
|
+
### Watching the agent get told "no"
|
|
280
|
+
|
|
281
|
+
`make demo` makes the point on synthetic data, where the refusal is easy — there
|
|
282
|
+
was never any edge to find. The harder and more useful question is what happens
|
|
283
|
+
when a proposal *does* look good. `make demo-agent` runs one full research
|
|
284
|
+
session on **real market data** and narrates every guardrail as it fires:
|
|
285
|
+
|
|
286
|
+
```text
|
|
287
|
+
$ make demo-agent
|
|
288
|
+
|
|
289
|
+
── Round 1 ────────────────────────────────────────────────────
|
|
290
|
+
Hypothesis Caching the processed universe to local disk lets the
|
|
291
|
+
strategy reuse warm state across sessions...
|
|
292
|
+
Sandbox REJECTED — generated code may not import 'os'
|
|
293
|
+
↳ no bars loaded, no backtest run, no trial consumed
|
|
294
|
+
|
|
295
|
+
── Round 2 ────────────────────────────────────────────────────
|
|
296
|
+
Sandbox REJECTED — MultiFactorConfluenceStrategy has 8 searchable params (cap 5)
|
|
297
|
+
|
|
298
|
+
── Round 4 ────────────────────────────────────────────────────
|
|
299
|
+
Proposal [code] new strategy implementation
|
|
300
|
+
Sandbox ADMITTED — imports clean, contract valid, params within cap
|
|
301
|
+
Walk-forward in-sample Sharpe 2.04 → out-of-sample 1.39 (efficiency 0.76)
|
|
302
|
+
Multiple-testing correction applied over 37 trials
|
|
303
|
+
Promotion gates:
|
|
304
|
+
[PASS] oos_sharpe 1.39 threshold 1.00
|
|
305
|
+
[PASS] oos_profit_factor 1.92 threshold 1.30
|
|
306
|
+
[PASS] walk_forward_efficiency 0.76 threshold 0.40
|
|
307
|
+
[FAIL] oos_drawdown_vs_is 18.40% threshold 13.50%
|
|
308
|
+
[FAIL] min_oos_trades 52 threshold 100
|
|
309
|
+
[PASS] deflated_sharpe 0.580 threshold 0.500
|
|
310
|
+
Verdict NOT promotable — discarded
|
|
311
|
+
```
|
|
312
|
+
|
|
313
|
+
That last round is the one worth dwelling on. The strategy is *not* noise: it
|
|
314
|
+
survives out-of-sample with a Sharpe of 1.39 and clears four of six gates. It is
|
|
315
|
+
refused anyway, because 52 out-of-sample trades is too small a sample to
|
|
316
|
+
distinguish skill from luck and its drawdown degraded relative to in-sample. A
|
|
317
|
+
research engine that only rejects obvious garbage is not doing anything for you;
|
|
318
|
+
the interesting behavior is rejecting things that look good.
|
|
319
|
+
|
|
320
|
+
By default the proposals are **replayed** from a fixed set, so the run is
|
|
321
|
+
deterministic and needs no LLM API key — only Alpaca market-data keys. Point it
|
|
322
|
+
at a live model to watch it improvise instead:
|
|
323
|
+
|
|
324
|
+
```bash
|
|
325
|
+
make demo-agent # replayed proposals, deterministic
|
|
326
|
+
make demo-agent-live # live Claude proposer (needs ANTHROPIC_API_KEY)
|
|
327
|
+
|
|
328
|
+
uv run python main.py demo-agent --symbols NVDA,AAPL,META --provider ollama
|
|
329
|
+
```
|
|
330
|
+
|
|
331
|
+
Real market data means real variance: the exact Sharpes and which gates fail will
|
|
332
|
+
differ with the universe and date range you point it at. The shape — proposals
|
|
333
|
+
rejected before evaluation, survivors gated on out-of-sample evidence, nothing
|
|
334
|
+
promoted automatically — is what stays constant.
|
|
335
|
+
|
|
336
|
+
## What it does
|
|
337
|
+
|
|
338
|
+
| Command | What happens |
|
|
339
|
+
|---------|--------------|
|
|
340
|
+
| `demo` | Run the whole pipeline on **synthetic data** — no keys, no network — ending in an honest promotion verdict |
|
|
341
|
+
| `demo-agent` | Narrate one AI research session on **real market data**: proposal → sandbox → walk-forward → gates → holdout |
|
|
342
|
+
| `init` | Guided first-run setup: write a valid `.env` with hidden prompts, validate the keys against Alpaca via the data-only client, confirm paper trading, optionally warm the cache. `--check` is a doctor that writes nothing |
|
|
343
|
+
| `scan` | Run the universe scanner and print flagged symbols |
|
|
344
|
+
| `verdict` | The whole cross-sectional pipeline in one command — scan → alphas → portfolio → information over one universe, one window, one cost model — ending in one gate-derived verdict (read-only) |
|
|
345
|
+
| `backtest` | Scan → run a strategy over history → performance report |
|
|
346
|
+
| `live` | Scan → warm up indicators → stream bars → place paper/live orders. Bar-quality guards (staleness, spikes, inconsistent OHLC, out-of-order) veto bad bars — rejecting, never repairing — and a position ledger records intent vs. observed fills |
|
|
347
|
+
| `live --dry-run` | What this contract **would** try to do right now: the orders it would send, the caps that would bind, the signals it would skip. The broker has no order methods that work, so trading is a capability it does not have rather than a rule it was told. No credentials, no fills, nothing journaled |
|
|
348
|
+
| `small-real` | **Places real orders.** Trades a validated config at reduced capital to measure fills, slippage and fees — the caps scaled with the book rather than shrunk by hand, since a ceiling small enough to force fills biases the sample toward low-priced names. Mandatory preflight, paper by default, telemetry to its own ledger, and no trial journaled |
|
|
349
|
+
| `reconcile` | Check the position ledger against the broker's actual account state. Reports divergence; never corrects it (read-only) |
|
|
350
|
+
| `halt` / `resume` / `halts` | Stop opening new positions, and say so durably — a running engine sees it on the next bar. Blocks entries, never exits, so it can't trap the book |
|
|
351
|
+
| `flatten` | Emergency: halt, cancel every order, close every position. Goes straight to the broker, so it works when the engine is wedged |
|
|
352
|
+
| `backtest --causality` | Probe whether each decision could have been made when it was made: the execution clock, same-bar ranking, benchmark alignment, and the scanner's as-of clock. A **different class** from the leakage probe, which tests for future data and cannot see a one-bar look-ahead at all |
|
|
353
|
+
| `screen` | Sweep a parameter space cheaply to ask whether a family holds anything at all — one process, one data fetch, N evaluations, and **nothing journaled**. Leads with the distribution and what the best of N draws is worth under the null, because the best of N is the maximum of N draws; `--confirm` records exactly one point as a real trial |
|
|
354
|
+
| `optimize` | Search strategy parameters by backtest objective (grid / random / Bayesian); `--workers N` evaluates candidates in parallel — wall-clock only, same trials and same winner |
|
|
355
|
+
| `allocate` | Weight a portfolio: scalar-score sizing (OR-Tools), or `--objective utility` for mean-variance construction from alpha + Σ |
|
|
356
|
+
| `alphas` | Rank a universe by continuous alpha — a comparable, annualized residual-return forecast per name; `--combine` blends several signals, `--neutralize-factors` regresses out the risk model's factor exposures (read-only) |
|
|
357
|
+
| `risk` | Estimate the universe covariance Σ (Ledoit–Wolf shrinkage) and summarize its risk structure (read-only) |
|
|
358
|
+
| `info` | Information report: measure IC, breadth, and predicted-vs-realized IR — skill vs luck (read-only) |
|
|
359
|
+
| `--html PATH` | On `verdict`/`backtest`/`walkforward`/`info`: write a self-contained HTML report of the run — inline charts, zero external requests, provenance and honesty warnings first-class |
|
|
360
|
+
| `horizon` | Measure alpha decay / half-life; recommend rebalance cadence + current/lagged blend (read-only) |
|
|
361
|
+
| `walkforward` | Out-of-sample validation: optimize in-sample, score out-of-sample across folds, with a sacred holdout and promotion gates |
|
|
362
|
+
| `trials` | Browse the campaign's memory: `list` (filters, sorting, paging), `show` (one trial in full), `best` (a DSR-ranked leaderboard that always shows the family's `n_trials`) — read-only; `archive` retires a whole era by moving the journal and its index aside **together** (a store left beside a fresh journal keeps reporting a trial count for evidence that is gone); `mark-contaminated` quarantines a suspect subset with an appended event — history intact, reason on the record |
|
|
363
|
+
| `mcp` | Serve QuantRed over MCP so an agent (Claude Code / Desktop) can drive verdict/scan/backtest/optimize/walk-forward/alphas/risk/portfolio/info — read-only, no live trading |
|
|
364
|
+
|
|
365
|
+
One strategy ships, and it is a demonstration rather than a candidate:
|
|
366
|
+
|
|
367
|
+
- **`demo_trend`** — long-only EMA trend follower: the normalized fast−slow gap,
|
|
368
|
+
whose sign crossings are the golden / death cross (daily). Paired with the
|
|
369
|
+
`demo_volume` scanner.
|
|
370
|
+
|
|
371
|
+
It exists so `quantred demo` has something to run and so the interface has a
|
|
372
|
+
worked example, not because it is an edge — the demo above spends its whole output
|
|
373
|
+
showing that it is not. **The strategies you would actually trade go in your own
|
|
374
|
+
package**, installed beside the engine and discovered by entry point, which keeps
|
|
375
|
+
them out of this repository entirely.
|
|
376
|
+
|
|
377
|
+
Each strategy defines a single continuous **score** (its conviction); the trade
|
|
378
|
+
clock's `BUY/SELL/HOLD` and the
|
|
379
|
+
[continuous alpha](https://tradeflow.mk-dir.com/engineering/alphas) are both
|
|
380
|
+
derived from it — one source of truth.
|
|
381
|
+
|
|
382
|
+
`example` is a complete working pack to copy — `quantred init
|
|
383
|
+
--example-pack ./my-signals` writes it out. See
|
|
384
|
+
[Your own strategies](https://tradeflow.mk-dir.com/usage/private-strategies)
|
|
385
|
+
and [Extending](https://tradeflow.mk-dir.com/engineering/extending).
|
|
386
|
+
|
|
387
|
+
### Using it from your own code
|
|
388
|
+
|
|
389
|
+
`quantred.services.*` is the supported surface — the same JSON-returning functions
|
|
390
|
+
the CLI renders and the MCP server exposes, so you get identical numbers by
|
|
391
|
+
construction:
|
|
392
|
+
|
|
393
|
+
```python
|
|
394
|
+
from quantred.services.analysis import run_verdict
|
|
395
|
+
from quantred.services.data import build_data_client
|
|
396
|
+
|
|
397
|
+
result = run_verdict(build_data_client(), "demo_trend", ["NVDA", "AAPL"], start, end)
|
|
398
|
+
print(result["verdict"]["summary"])
|
|
399
|
+
```
|
|
400
|
+
|
|
401
|
+
Everything outside `services/` is internal and moves without notice. See
|
|
402
|
+
[Using QuantRed as a library](https://tradeflow.mk-dir.com/engineering/embedding).
|
|
403
|
+
|
|
404
|
+
### Optional features
|
|
405
|
+
|
|
406
|
+
Capabilities are optional extras so the base install stays lean:
|
|
407
|
+
|
|
408
|
+
Installed: see the [extras guide](https://tradeflow.mk-dir.com/usage/extras). In a
|
|
409
|
+
checkout:
|
|
410
|
+
|
|
411
|
+
```bash
|
|
412
|
+
make install-optimize # scikit-learn, for `optimize --method bayesian`
|
|
413
|
+
make install-portfolio # Google OR-Tools, for `allocate`
|
|
414
|
+
uv sync --inexact --extra mcp # the MCP SDK, for `python main.py mcp`
|
|
415
|
+
```
|
|
416
|
+
|
|
417
|
+
## Project status
|
|
418
|
+
|
|
419
|
+
This is an evolving research project, not a production trading platform. To keep
|
|
420
|
+
that honest, here's what's load-bearing versus what's still maturing:
|
|
421
|
+
|
|
422
|
+
| Capability | Status |
|
|
423
|
+
|------------|--------|
|
|
424
|
+
| Broker / market-data abstractions | ✅ Stable |
|
|
425
|
+
| Offline backtesting + analytics | ✅ Stable |
|
|
426
|
+
| Pure pandas/numpy indicators | ✅ Stable |
|
|
427
|
+
| Universe scanning | ✅ Stable |
|
|
428
|
+
| Offline test suite (in-memory fakes) | ✅ Stable |
|
|
429
|
+
| Parameter optimization — grid / random | ✅ Stable |
|
|
430
|
+
| Walk-forward validation + promotion gates | 🧪 Experimental |
|
|
431
|
+
| Parameter optimization — Bayesian | 🧪 Experimental |
|
|
432
|
+
| Portfolio allocation (OR-Tools) | 🧪 Experimental |
|
|
433
|
+
| Live paper trading | 🧪 Experimental |
|
|
434
|
+
| Bar-quality guards + position reconciliation | 🧪 Experimental |
|
|
435
|
+
| MCP server | 🧪 Experimental |
|
|
436
|
+
| Research agent | 🧪 Experimental |
|
|
437
|
+
|
|
438
|
+
"Experimental" means the interfaces and gate thresholds may still change — not
|
|
439
|
+
that the code is untested. Everything ships with offline tests.
|
|
440
|
+
|
|
441
|
+
## Agent integration (MCP)
|
|
442
|
+
|
|
443
|
+
> **AI-assisted research without AI-controlled trading.**
|
|
444
|
+
|
|
445
|
+
`quantred mcp` exposes QuantRed's deterministic capabilities to any MCP
|
|
446
|
+
client (Claude Code / Claude Desktop) as tools: discovery, `run_verdict`,
|
|
447
|
+
`run_scan`, `run_backtest`, `run_optimization`, `run_walk_forward`, the research
|
|
448
|
+
chain (`compute_alphas`, `construct_portfolio`, `compute_information`, ...),
|
|
449
|
+
`render_report`, read-only trial-store access (`list_trials`, `get_trial`,
|
|
450
|
+
`best_trials`), `get_metrics_glossary`, and `save_config`/`load_config`/
|
|
451
|
+
`list_configs`. Every call is appended to the audit log (`logs/mcp_audit.jsonl` under the state root) for replay.
|
|
452
|
+
|
|
453
|
+
**The safety model is structural.** The server constructs only a *data* client —
|
|
454
|
+
no trading client, no broker — so it is incapable of placing an order. There is
|
|
455
|
+
no `place_order`, `start_live`, `cancel`, or `set_paper_trade` tool; promoting a
|
|
456
|
+
config to live is a manual human step outside MCP. The capability simply isn't
|
|
457
|
+
wired in, so it can't be prompt-injected around. The agent works on the
|
|
458
|
+
*research clock* (offline, exploratory); the live order path stays LLM-free.
|
|
459
|
+
|
|
460
|
+
Register it with a client. The server needs the `mcp` extra, which the quickstart above
|
|
461
|
+
installs; on a copy that lacks it, `quantred init --check --for mcp` prints the one command
|
|
462
|
+
that adds it and keeps your other extras and packs:
|
|
463
|
+
|
|
464
|
+
```bash
|
|
465
|
+
claude mcp add quantred -- quantred mcp # Claude Code
|
|
466
|
+
```
|
|
467
|
+
|
|
468
|
+
```json
|
|
469
|
+
{ "mcpServers": { "quantred": { "command": "quantred", "args": ["mcp"] } } }
|
|
470
|
+
```
|
|
471
|
+
|
|
472
|
+
A desktop client often has a smaller `PATH` than a terminal, so `quantred init` prints
|
|
473
|
+
this block with the absolute command for your copy, and `quantred mcp --self-test`
|
|
474
|
+
runs exactly that command (printing the block again when it passes). From a checkout it is the checkout's interpreter and the
|
|
475
|
+
absolute `main.py`:
|
|
476
|
+
|
|
477
|
+
```json
|
|
478
|
+
{ "mcpServers": { "quantred": {
|
|
479
|
+
"command": "/path/to/quantred/.venv/bin/python",
|
|
480
|
+
"args": ["/path/to/quantred/main.py", "mcp"] } } }
|
|
481
|
+
```
|
|
482
|
+
|
|
483
|
+
An installed copy and a checkout share one state root, `~/.tradeflow`, unless
|
|
484
|
+
`TRADEFLOW_HOME` is set, so an agent and you see the same campaign history. If you set
|
|
485
|
+
`TRADEFLOW_HOME`, the config block printed by `init` carries it too; a desktop client does
|
|
486
|
+
not inherit your shell's exports.
|
|
487
|
+
|
|
488
|
+
## Research agent (optional)
|
|
489
|
+
|
|
490
|
+
`quantred research` runs a bounded, offline loop that proposes hypotheses,
|
|
491
|
+
validates them out-of-sample with walk-forward, and writes a shortlist of
|
|
492
|
+
provenance-stamped candidate configs to `configs/` for a human to review. It never
|
|
493
|
+
promotes anything to live trading.
|
|
494
|
+
|
|
495
|
+
The proposer is **provider-agnostic** — choose with `--provider`:
|
|
496
|
+
|
|
497
|
+
| Provider | Install | Default model | Credential |
|
|
498
|
+
|----------|---------|---------------|------------|
|
|
499
|
+
| `anthropic` (default) | extra `ai` | `claude-opus-4-8` | `ANTHROPIC_API_KEY` |
|
|
500
|
+
| `openai` | extra `openai` | `gpt-4o` | `OPENAI_API_KEY` |
|
|
501
|
+
| `ollama` (local) | none | `llama3.1` | none |
|
|
502
|
+
|
|
503
|
+
`quantred init --check --for research --provider anthropic` prints the exact command that
|
|
504
|
+
adds the extra to your copy. Set the credential in `.env` (alongside your Alpaca keys; `quantred init`
|
|
505
|
+
writes it) or as the standard environment variable. Ollama runs locally and needs no key.
|
|
506
|
+
|
|
507
|
+
```bash
|
|
508
|
+
quantred research --provider ollama --model llama3.1 \
|
|
509
|
+
--symbols NVDA,AAPL --start 2024-01-01 --end 2025-12-31 \
|
|
510
|
+
--goal "improve OOS Sharpe without raising max drawdown" --holdout-days 60
|
|
511
|
+
```
|
|
512
|
+
|
|
513
|
+
See the [docs](https://tradeflow.mk-dir.com/) (Usage → *AI agents*) for the full
|
|
514
|
+
tool surface, guardrails, and provider setup.
|
|
515
|
+
|
|
516
|
+
*Contributors, from a checkout:* the same commands run as `python main.py mcp` and
|
|
517
|
+
`python main.py research`, and extras are added with `uv sync --inexact --extra ai`
|
|
518
|
+
(`--inexact` keeps the dev tools and any editable pack).
|
|
519
|
+
|
|
520
|
+
## Architecture
|
|
521
|
+
|
|
522
|
+
The codebase is organized into single-responsibility layers. Nothing above the
|
|
523
|
+
broker layer imports a vendor SDK. The two clocks never touch — automation only
|
|
524
|
+
ever proposes a config; a human promotes it:
|
|
525
|
+
|
|
526
|
+
```mermaid
|
|
527
|
+
flowchart LR
|
|
528
|
+
subgraph research["Research clock — offline · LLM-allowed"]
|
|
529
|
+
direction TB
|
|
530
|
+
H[hypothesis] --> B[backtest] --> O[optimize] --> W[walk-forward]
|
|
531
|
+
W --> C[(provenance-stamped<br/>config)]
|
|
532
|
+
end
|
|
533
|
+
subgraph trade["Trade clock — live · deterministic · LLM-free"]
|
|
534
|
+
direction TB
|
|
535
|
+
Bar[live bar] --> Sig[signal] --> Ord[broker order]
|
|
536
|
+
end
|
|
537
|
+
C -. "human promotes<br/>(nothing auto-flips)" .-> Bar
|
|
538
|
+
```
|
|
539
|
+
|
|
540
|
+
The layers themselves:
|
|
541
|
+
|
|
542
|
+
```
|
|
543
|
+
brokers/ Broker interface + domain types ── alpaca/ (AlpacaBroker, AlpacaMarketData)
|
|
544
|
+
marketdata/ MarketDataProvider interface, Timeframe, MarketDataClient
|
|
545
|
+
indicators/ Pure pandas/numpy technical indicators
|
|
546
|
+
strategies/ Strategy base + signals (score -> BUY/SELL/HOLD, sizing, risk)
|
|
547
|
+
scanners/ ScannerStrategy base + SymbolScanner (universe resolution)
|
|
548
|
+
demo/ The one strategy + scanner a bare install ships, for `quantred demo`
|
|
549
|
+
execution/ LiveTrader (signals -> broker orders)
|
|
550
|
+
analytics/ Performance metrics + reporting
|
|
551
|
+
engine/ BacktestEngine + LiveEngine (orchestration only)
|
|
552
|
+
optimization/ ParameterSpace + ParameterOptimizer (tune params via backtest)
|
|
553
|
+
portfolio/ PortfolioAllocator (OR-Tools MIP position weighting)
|
|
554
|
+
utils/ logging, numeric, time helpers
|
|
555
|
+
```
|
|
556
|
+
|
|
557
|
+
Data flows the same way in both modes:
|
|
558
|
+
|
|
559
|
+
```
|
|
560
|
+
marketdata → strategy.process_data → strategy.generate_signals
|
|
561
|
+
→ engine (simulate fills | route to execution) → analytics
|
|
562
|
+
```
|
|
563
|
+
|
|
564
|
+
To work on them locally:
|
|
565
|
+
|
|
566
|
+
```bash
|
|
567
|
+
make docs # serve the Docusaurus site at http://localhost:3000
|
|
568
|
+
```
|
|
569
|
+
|
|
570
|
+
## Docker
|
|
571
|
+
|
|
572
|
+
```bash
|
|
573
|
+
make docker-build
|
|
574
|
+
make docker-run # paper live-trading; mounts your .env
|
|
575
|
+
```
|
|
576
|
+
|
|
577
|
+
## Tests
|
|
578
|
+
|
|
579
|
+
```bash
|
|
580
|
+
make test # offline suite — no API keys or network required
|
|
581
|
+
```
|
|
582
|
+
|
|
583
|
+
The whole stack is testable offline because every layer depends on the
|
|
584
|
+
broker/data abstractions; tests inject in-memory fakes.
|
|
585
|
+
|
|
586
|
+
Lint and format with ruff (what CI runs):
|
|
587
|
+
|
|
588
|
+
```bash
|
|
589
|
+
uv run ruff check . # lint
|
|
590
|
+
uv run ruff format --check . # format
|
|
591
|
+
```
|
|
592
|
+
|
|
593
|
+
## Contributing
|
|
594
|
+
|
|
595
|
+
**Contributions and ideas are very welcome** — whether it's a bug fix, a new
|
|
596
|
+
strategy or scanner, an additional broker/data adapter, an LLM provider, docs, or
|
|
597
|
+
just a feature request or suggestion. If you have an idea, open an issue to start
|
|
598
|
+
the conversation; if you have a fix, open a PR. No contribution is too small, and
|
|
599
|
+
feedback on what would make QuantRed more useful is always appreciated.
|
|
600
|
+
|
|
601
|
+
And hey — don't be greedy: share your algos, let's make money together. 📈 (Worst
|
|
602
|
+
case, we lose money together, which is basically friendship.)
|
|
603
|
+
|
|
604
|
+
See **[CONTRIBUTING.md](CONTRIBUTING.md)** for setup, the pre-push checks, and the
|
|
605
|
+
coding standards (layering rules, separation of concerns, no vendor SDK above the
|
|
606
|
+
broker layer). CI runs ruff lint + format + the test suite on every PR.
|
|
607
|
+
|
|
608
|
+
## Stopping, and account utilities
|
|
609
|
+
|
|
610
|
+
`Ctrl-C` stops the process but records nothing — restart the engine and it trades
|
|
611
|
+
again. To stop in a way that sticks:
|
|
612
|
+
|
|
613
|
+
```bash
|
|
614
|
+
make halt REASON="feed looks wrong" # refuse new entries; exits still allowed
|
|
615
|
+
make halts # what is currently halted
|
|
616
|
+
make resume # lift it
|
|
617
|
+
make flatten REASON="why" # halt, cancel everything, close everything
|
|
618
|
+
```
|
|
619
|
+
|
|
620
|
+
Halt state is a file under the state root, not a database — the order path holds no
|
|
621
|
+
connection to anything that can be down, so the switch still works when the engine
|
|
622
|
+
does not. See [Stopping trading](https://tradeflow.mk-dir.com/usage/stopping).
|
|
623
|
+
|
|
624
|
+
## ☕ Coffee?
|
|
625
|
+
|
|
626
|
+
If this code somehow makes you money, I'd genuinely love to hear about it. If it
|
|
627
|
+
*loses* you money — we've never met, and this is the first you're hearing of it.
|
|
628
|
+
|
|
629
|
+
Either way, if it saved you some time, you can buy me a coffee:
|
|
630
|
+
|
|
631
|
+
**[buy me a coffee →](https://venmo.com/u/Andrew-Schwartz-92)**
|
|
632
|
+
|